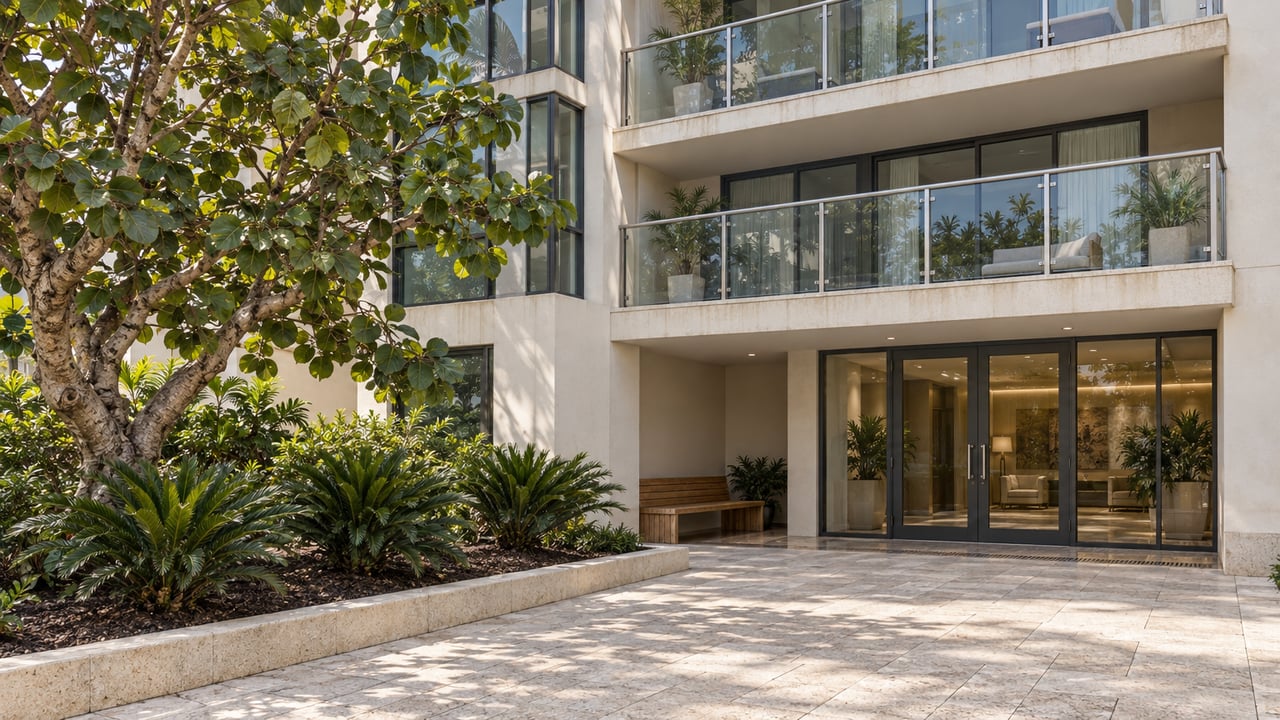
In December 2023, David Stern closed on a $1.8 million unit at Amrit Ocean Resort, the two-tower oceanfront project at 3100 North Ocean Drive on Singer Island. The next year he sued over control of the condo association. The case settled in May 2026, and control has since been turned over to the owners. His purchase now sits inside one of the most closely watched buildings on the island. The lesson for anyone shopping Singer Island condos this fall has less to do with one building than with a federal rule change that took effect two months ago.
On Aug. 3, 2026, conventional condo lending in Florida changed. Now the lender studies the building as closely as it studies the borrower, and a large down payment no longer lets a borrower skip that review.
What Aug. 3 Actually Removed
Most coverage of the change was about the down payment. Rep. Byron Donalds announced in March that Florida condo borrowers had "been harshly subject to a 25% down payment" under the Fannie Mae and Freddie Mac Limited Review process. He said Floridians would now have access to down payments "ranging from 3% to 5%." That can happen, but only when both the loan and the building qualify.
The other half of the change matters more on Singer Island. Fannie Mae's Lender Letter LL-2026-03 retired Limited Review completely. Established projects must now go through Full Review or, when eligible, a Waiver of Project Review. Lenders must follow the new rule for every loan application dated on or after Aug. 3, 2026. Freddie Mac retired its Streamlined Review on the same date. The expanded waiver covers projects of ten or fewer units, so it does nothing for an oceanfront high-rise.
Florida Realtors described those retired options as paths that let certain established buildings get "a less extensive review." Under the old system, the buyer who put 25% down accepted a higher cash requirement and got a lighter look at the building in return. That trade is gone. Full Review, in the same article's words, requires lenders to look at "the condo project itself, not just the buyer," including the association's budget, reserves, insurance and financial condition.
FHA is not much of a fallback. MIAMI Realtors reported in September 2026 that only 21 of the 2,397 condominium buildings in Miami-Dade, Broward and Palm Beach counties were approved for FHA loans. For most financed buyers, the conventional Full Review is the only route.
A Newer Tower Is Not Automatically Easier to Finance
Buyers often assume the newest building on the beach is the easiest to finance. Amrit shows why that doesn't hold.
The Palm Beach Post describes Amrit as a 351-unit twin-tower complex, with 182 of those units residential. The city lists the complex as a hotel. Under that designation, residents can't claim the homestead property tax exemption, and the Post reports it has also kept some of them from getting mail. Councilman Glen Spiritis, whose district includes that stretch of the island, told the Post that "Every room in the Amrit is a hotel room." An Amrit spokesperson said all zoning requirements, including the bar on permanent residences, were clearly disclosed in the purchase agreements.
The owners have filed a formal application with Riviera Beach to reclassify all 182 units as condominiums. Jason Detar, president of the Amrit Ocean Resort Condominium Association, said the application meets the applicable parking requirements. The city's conversion process usually costs $52,500 per unit. In July, a preliminary review by Clarence Sirmons, the city's director of development services, found that parking and density rules would limit conversion to 60 units. The owners dispute that figure and are asking the city to cut the fee to $1,000 per applicable unit or waive it. The council got an update on Sept. 22. The final decision rests with the city council, and making the change official would take two votes.
A separate matter is still in court. In May 2026, the association sued the developer entities and the construction team, which includes Optimal Construction, Paramount Consulting & Engineering, S&E Architects and CAP Government. The suit alleges roof leaks, corrosion in building systems, cracking stucco and deteriorating concrete. Amrit "strongly rejects claims of 'shoddy construction,'" and as of June the case was ongoing.
"Every room in the Amrit is a hotel room. It is not a condominium. It was approved as a hotel. It was built as a hotel." Riviera Beach City Council member Glen Spiritis, as quoted by The Real Deal in May 2026
None of this settles whether a lender would approve or decline any particular Amrit unit. That decision belongs to the lender, after a project review. The case does show what a Full Review looks for, which is the subject of the next section.
The Two Categories That End a Loan File
Freddie Mac's Guide Section 5701.3 lists the project types it won't buy loans on. Two of them apply directly to oceanfront towers that share amenities, operators or a history with a hotel.
| Freddie Mac ineligibility category | Examples the guide lists | What to ask before an offer |
|---|---|---|
| Condominium hotel | Hotel or motel licensing or registration; mandatory rental pooling or blackout dates on owner use; revenue sharing with the HOA or its rental operator | How is the property licensed or registered, and does any agreement limit when owners can live in their units? |
| Transient housing | Conversion from a hotel without a gut rehabilitation; HOA-run registration desk; a required rental agency; HOA collecting and paying hotel or short-term rental taxes; HOA limits on interior decorating | Who runs rentals in the building, and does the HOA earn revenue or pay expenses for hotel-type services? |
| Project in litigation | The HOA or the developer is a party to pending litigation or arbitration about safety, structural soundness, functional use or habitability | Is the association in any pending suit or arbitration, and what does the complaint cover? |
The litigation rule has narrow exceptions, and buyers should know them. A lawsuit can still pass if it involves only minor matters and fits one of several cases. Examples include a claim the HOA's insurer has committed to defend and cover, an HOA suing to recover money it already spent on a repair that permanently fixed the problem, or an amount in dispute that isn't expected to exceed 10% of the project's funded reserves. So two buildings can both be "in litigation" and get opposite answers from the same lender.
Older Towers Carry a Different Kind of Risk
The island's older stock is reviewed under the same rules but tends to raise different issues. Florida requires milestone structural inspections for condo buildings three or more habitable stories high once they reach 30 years, or 25 where the local agency sets that earlier age, and every 10 years after that. Freddie Mac requires lenders to examine each current or planned special assessment, including its purpose, approval date, amount and collection status, to determine whether it pays for a critical repair.
Assessments on the island have been large before. In September 2024, a Dunes Towers resident told CBS12 she had recently paid a $70,000 assessment for concrete, plumbing and other repairs and expected more. That was one owner's account, two years old. It shows the kind of line item a lender now has to explain before approving a loan.
The calendar adds another deadline. Starting with applications dated on or after Jan. 4, 2027, Fannie Mae's minimum replacement-reserve allocation under Full Review rises from 10% to 15% of the annual budgeted assessment income. Since Aug. 3, a building that relies on a reserve study must also budget the study's highest recommended allocation, and the baseline funding method is no longer allowed. A building whose budget clears the review this fall could fall short for a buyer whose loan application is dated in January.
What the Supply Numbers Mean for a Financed Buyer
Public data isn't broken out for Singer Island alone, but the countywide numbers show who has leverage. In August 2026, Palm Beach County's condo and townhouse market had 6.7 months of supply and a $300,000 median sale price, up 5.3% from August 2025. Inventory was 5,770 listings, down 17.1%. Single-family homes in the county had 3.5 months of supply over the same period. The next monthly release is scheduled for Oct. 16.
A financed condo buyer has nearly twice as many months of choices as a house buyer, so walking away from a building whose documents won't clear a lender's review costs less. Sellers in buildings with a clean budget, clear classification and no open safety-related litigation can now show financed buyers something many competing listings can't.
The island will add more stock. Singer Island Gateway, a proposed 28-story, 298-residence tower on the Intracoastal west of 2525 Lake Drive, by The Continuum Co. with Arquitectonica as architect, was still in city staff review as of March 2026. It hasn't been approved, and no delivery date has been reported.
The Paperwork to Request Before an Offer
Fannie Mae doesn't publish its project eligibility decisions. Its public Condo Project Status Finder also states that a "No findings" result doesn't mean a project has been reviewed or approved. Your lender has to check the building's status, and the review runs on these documents:
- The current association budget, showing the reserve line as a share of assessment income
- The latest reserve study and Structural Integrity Reserve Study, plus whether the budget funds the highest recommended allocation
- Any milestone inspection report, and whether the building has reached its inspection age
- Every current or planned special assessment, with its purpose, approval date, amount and collection status
- A written disclosure of any pending litigation or arbitration involving the association or developer, along with the complaint
- The declaration and any rental, management or operator agreements, checked against the condo-hotel and transient-housing examples in the table above
- The lender's own status check on the project, ordered before the inspection period ends
Florida Realtors warned in May that full reviews could cause financing delays tied to documents. Getting the file to your lender early helps prevent that. For tax questions about homestead and legal questions about a building's governing documents, ask a licensed tax professional and a real estate attorney.
If you're comparing Singer Island towers and plan to finance, IJL Real Estate Group can help you request association documents and get them to your lender early, so you know whether a building can clear Full Review before you make an offer. Book an appointment with Ivy to go through the towers on your list.